Local claim risks in Sparks
- Truckee River flooding
- Wind
- Wildfire smoke
- Frozen pipes
- Commercial roof damage
Housing mix: Railroad-era homes, 1970s–90s subdivisions, newer Spanish Springs homes, large warehouses.
Railroad roots, industrial growth
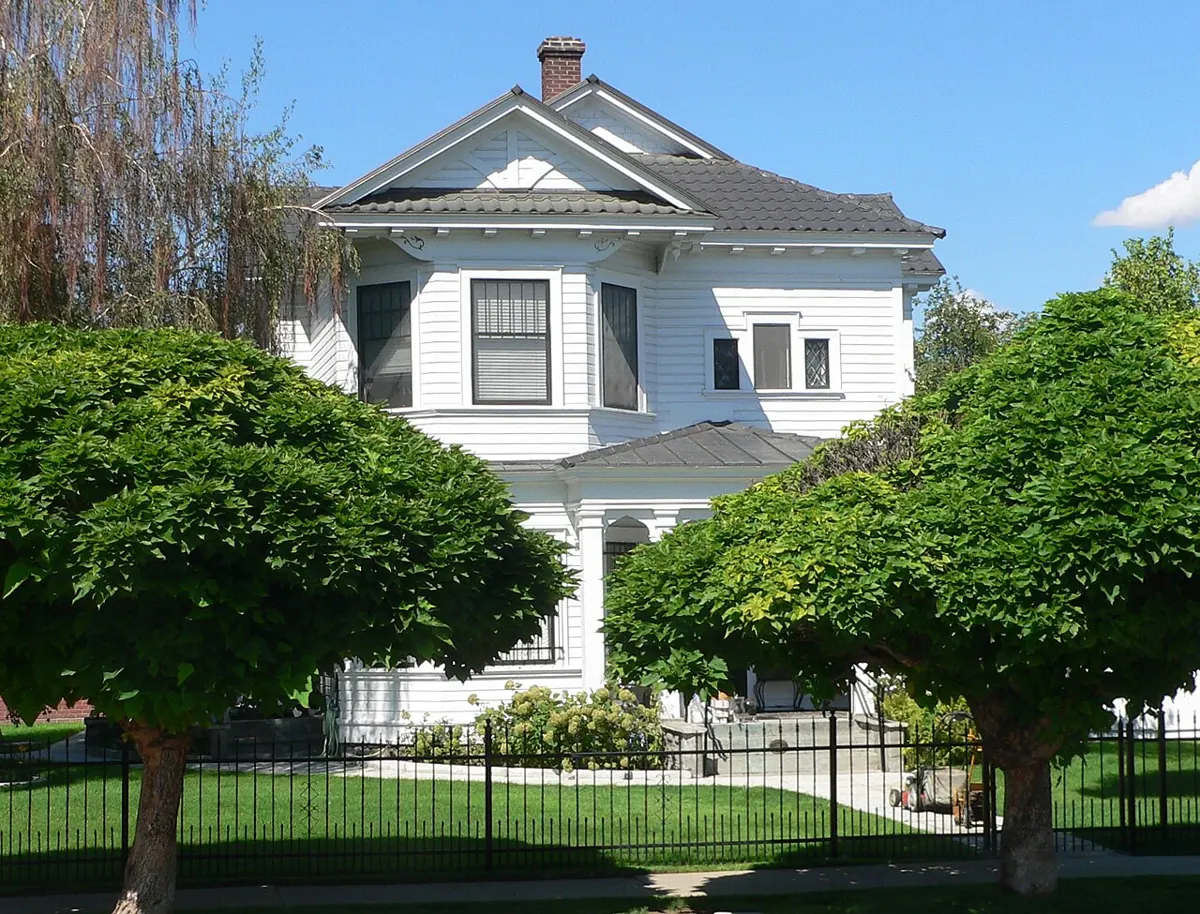
Sparks was founded around a Southern Pacific rail yard in the early 1900s, and a few homes from that era, like the restored Robison house, still stand. Most of the city’s housing came later: subdivisions from the 1970s through the 1990s, then Wingfield Springs, Spanish Springs, Kiley Ranch and the D’Andrea area as the city grew north and east. Along I-80, the industrial corridor holds some of the largest warehouse and distribution buildings in the region.
Risks that recur
- Truckee River flooding. The 1997 flood inundated much of the industrial area; flood claims usually fall under separate flood policies.
- Wind damaging roofs, fences and siding, especially on exposed ridges in Spanish Springs.
- Wildfire smoke drifting in from Sierra and Great Basin fires.
- Freeze damage to plumbing in older homes and vacant commercial space.
- Low-slope commercial roofs on warehouses, where small defects affect very large areas.
Areas we serve
Downtown Sparks and Victorian Square, Sparks Marina, Wingfield Springs, Spanish Springs, Kiley Ranch, D’Andrea, Pioneer Meadows and the industrial corridor along I-80 and USA Parkway.
Services in Sparks
Every Nevada Insurance Appraiser service is available to property owners in Sparks and the surrounding area, including:
- Appraisal Clause Representation
- Homeowner Claim Appraisal
- Commercial & HOA Claim Appraisal
- Roof & Hail Damage Appraisal
- Wind & Microburst Damage Appraisal
- Monsoon & Tropical Remnant Storm Appraisal
- Water & Slab Leak Damage Appraisal
- Fire & Smoke Damage Appraisal
Questions from Sparks property owners
Do you handle warehouse roof claims?
Yes. Large low-slope roofs need careful sampling and documentation, and we scope membranes, insulation and drainage separately.
My business was flooded. Can you help?
Flood losses usually fall under a separate flood policy with its own rules. If a covered peril under your commercial policy is involved, appraisal may apply to that part.