Where Nevada wind comes from
- The Washoe Zephyr. On warm afternoons, strong westerly winds pour off the Sierra into the Truckee Meadows. They are routine, but they test loose tile, fences and patio covers.
- Winter downslope events. Strong storm systems can send damaging gusts down the eastern slopes into Reno, Carson City and the Carson Valley.
- Monsoon microbursts. From roughly July through September, thunderstorm downdrafts in Southern Nevada can produce sudden, very strong straight-line winds over a small area: one neighborhood may see heavy damage while the next is untouched.
- Dust storms. Outflow winds can carry dust walls across the valley floor, sandblasting finishes and packing debris into HVAC units and pool equipment.
What wind does to Nevada buildings
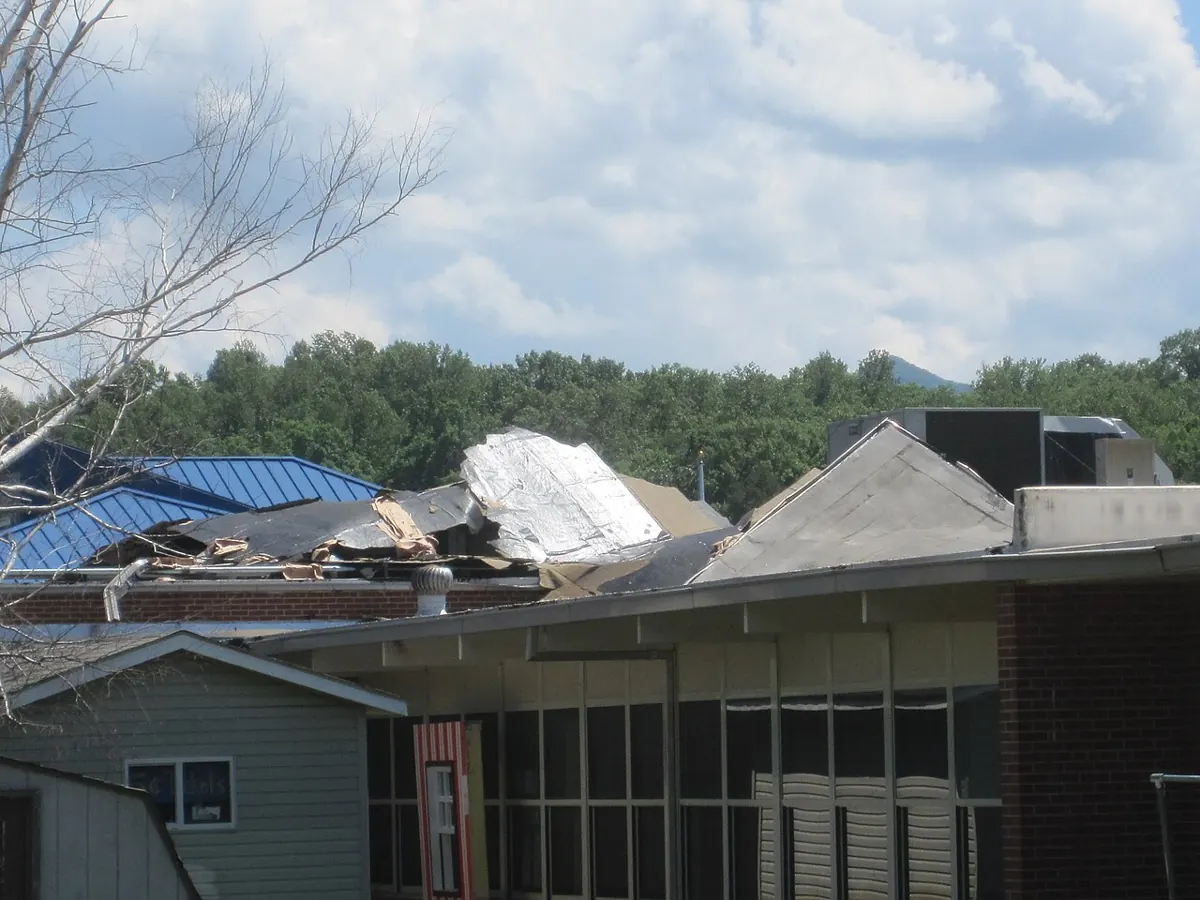
Lifted and displaced concrete tile, blown-off ridge and hip caps, torn shingles, collapsed patio covers and shade structures, toppled block walls and wood fences, broken windows and sliding doors, damaged rooftop and ground-mounted HVAC units, and solar panels pulled from their racking. Microbursts also drop large trees in older neighborhoods with mature landscaping.
Common disputes
Wind claims often turn on how much of the damage is new. Carriers may attribute displaced tile to age or prior repairs, or approve only the visibly missing pieces and not the disturbed tile around them. Block-wall claims raise questions about footing condition and code. We document each item with photos and measurements and tie it to the event date using weather data where available.
Questions about this service
Is a block wall covered under my homeowners policy?
Usually under ‘other structures’ (often Coverage B), which has its own limit. Whether the wall’s condition before the storm affects the claim depends on your policy and the facts.
Only part of my neighborhood was hit. Will the insurer believe me?
Microbursts are very localized. Weather records, neighbor reports and fresh damage patterns help show what happened at your address.
Do you handle solar panel damage?
Yes. We include panel removal and reinstallation, racking and roof penetrations in the scope when the roof or panels were damaged.