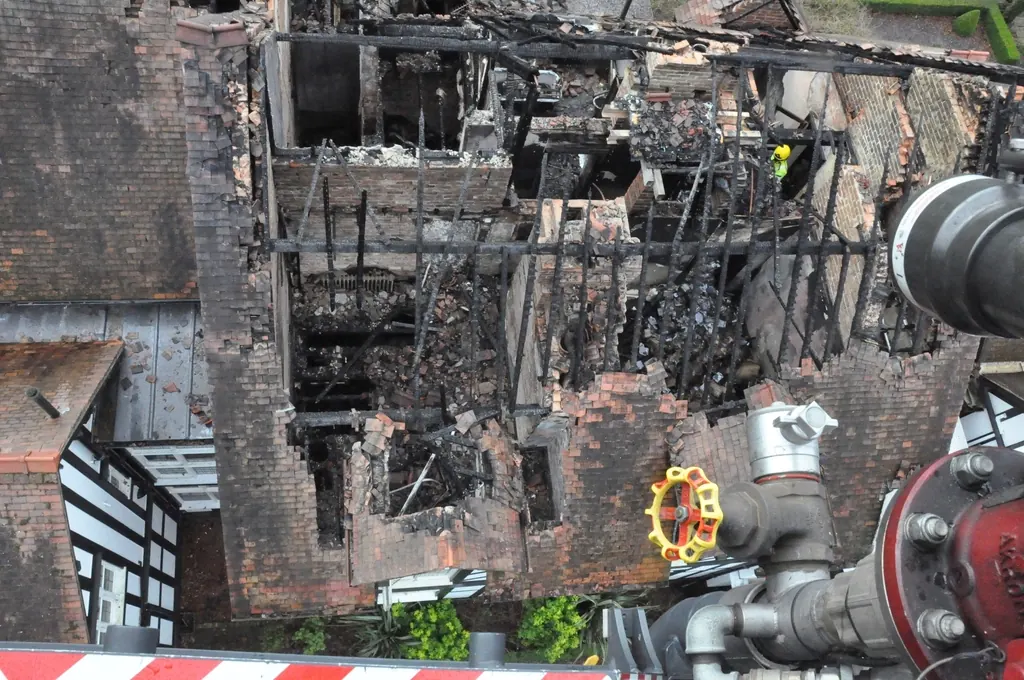
The burn, the smoke and everything in between
A kitchen or garage fire in a Las Vegas tract home can be contained to one room and still send smoke through every return-air vent in the house. In tight Nevada homes with attic air handlers, soot often settles on insulation, framing and duct interiors that nobody sees during a quick inspection. Synthetic materials in modern furnishings produce oily residue that is harder to clean than wood smoke.
Where fire estimates fall short
- Clean vs. replace. Carriers often price cleaning for surfaces that cannot be restored, such as porous textures or heat-distorted finishes.
- HVAC systems. Duct cleaning may not remove residue from flex duct; replacement is sometimes the correct scope.
- Attic and insulation. Smoke-laden insulation usually needs removal, attic cleaning and sealing before new insulation goes in.
- Odor control. Sealing framing, thermal fogging and hydroxyl or ozone treatment belong in the estimate when odor remains.
- Code items. Rebuilding may require upgraded electrical, smoke and carbon monoxide alarms or other current-code work, which ordinance-or-law coverage may address.
- Contents. Fire inventories can run to thousands of items. Grouped or averaged pricing understates them.
Our role
We scope the structure, systems and contents separately, price each repair method and explain why we chose it. For wildfire smoke and ash from outside the home, see our wildfire and ash damage service.
Questions about this service
The insurer only wants to clean my walls. Is that right?
Sometimes cleaning works. Sometimes it doesn’t, especially on textured or porous surfaces with heavy residue. Testing and documentation help settle it.
Can I appraise the contents portion of a fire claim?
Yes, if contents are part of the disputed amount of loss. A detailed inventory with ages, quantities and replacement prices is the foundation.
What about additional living expenses while we’re displaced?
ALE is usually handled by the adjuster and supported with receipts. We focus on the physical loss, but we can note how repair time affects ALE.